Participants in the market frequently credit enduring profits to accurate analysis, disciplined trading, or superior fundamental research. This focus on individuals misses a crucial financial truth: reliable long-term profits are much more reliant on structural positioning than on tactical ability. Even the most thorough analysis and disciplined execution cannot produce compounding returns without being aligned with prevailing capital flow hierarchies and market regime frameworks that influence asset valuation results.
If investors concentrate only on short-run tactical trading, they tend to ignore these major structural shifts and devote research energy to opportunities that run counter to mainstream capital movements. By first grasping how market regimes function, investors can place capital where long-term structural drivers facilitate wealth compounding, rather than swimming against strong systemic currents.
A clear micro-example can be seen in the performance discrepancies between assets that are fundamentally similar. Two securities exhibiting the same strength in balance sheets, cash flow situations, and growth predictions often yield differing return paths throughout market fluctuations. This divergence does not stem from operational distinctions, but rather from positional characteristics: eligibility for institutional benchmarks, usability for collateral, and access to passive capital flows. Assets that are integrated within essential financial structures maintain stable valuation support during volatility, whereas those on the periphery consistently endure capital withdrawal, irrespective of their fundamental quality.
Second-order systemic consequences reinforce this positional advantage over time. Assets that are well-positioned gather compounding structural advantages, such as reduced financing costs, greater liquidity depth, and more extensive analyst coverage. These qualities draw in ongoing institutional investments, generating self-perpetuating valuation momentum that detaches from minor fundamental changes. Positioning thus transforms from a fixed entry decision into a dynamic return enhancer, expanding performance disparities between core and peripheral market segments throughout complete economic cycles.
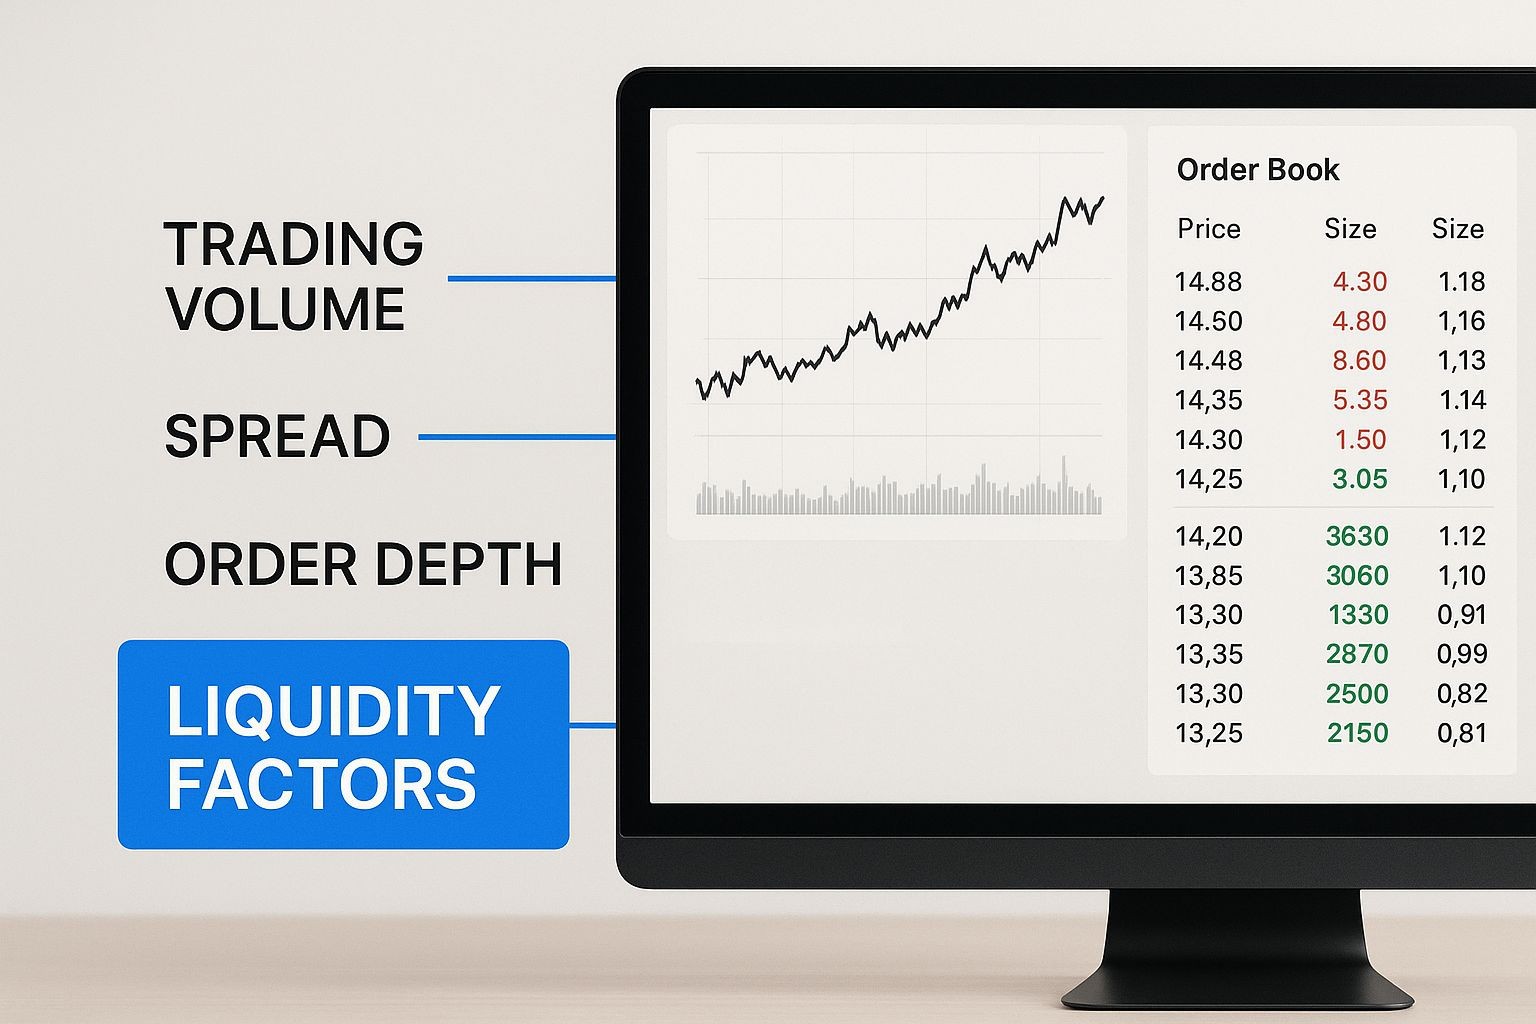
An essential paradox characterizes this positional profit framework. Financial markets tend to reward individual analytical diligence during limited short-term periods, while simultaneously penalizing isolated skill during regime transformations. Tactical trades based solely on singular fundamental insights may yield occasional profits but lack protective structural barriers. In the event of changes in liquidity regimes or institutional priorities, exposure without proper positioning is vulnerable to systemic rebalancing flows, nullifying accrued tactical gains in swift time frames.
Concealed positional risks alter the long-term vulnerability of portfolios in often unrecognized manners. Overdependence on familiar peripheral positioning generates subtle opportunity costs and exposure to cycles. Assets situated outside mainstream institutional frameworks demonstrate increased susceptibility to sentiment fluctuations and liquidity shrinkage, even when their underlying business performance remains consistent. This structural fragility can convert temporary market disturbances into enduring portfolio declines for allocations that are misaligned positionally.
For sophisticated cycle-aware allocation, the vital insight is to place structural alignment as a priority over tactical precision. Lasting profitability arises from securing positions favored by institutional capital regulations, liquidity hierarchies, and regime dynamics. An advanced market analysis assesses positional resilience prior to confirming fundamental attractiveness, distinguishing fleeting tactical profits from cycle-resilient structural returns. This viewpoint reshapes investment decision-making, acknowledging that lasting market success depends on consistent compatibility with unseen systemic financial frameworks.